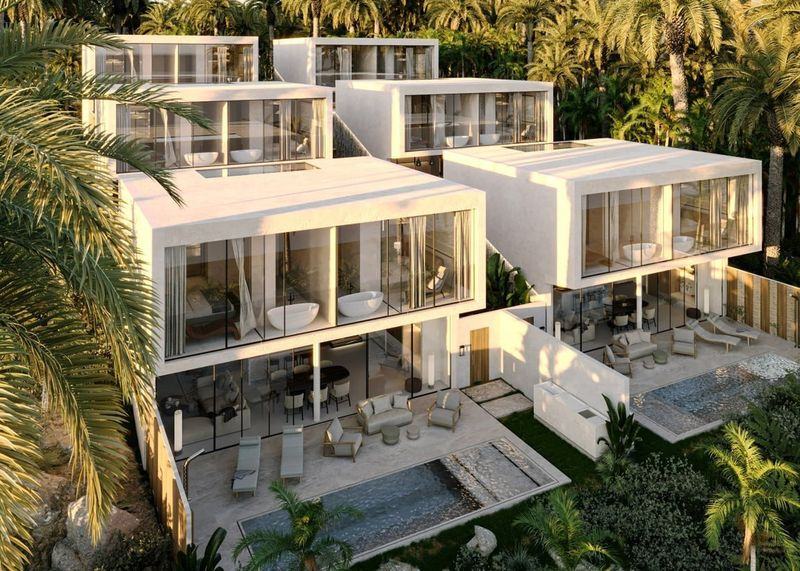
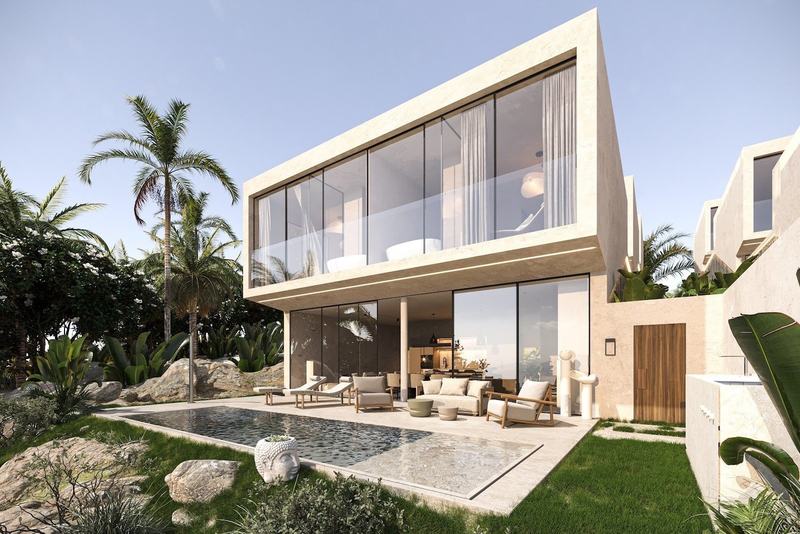
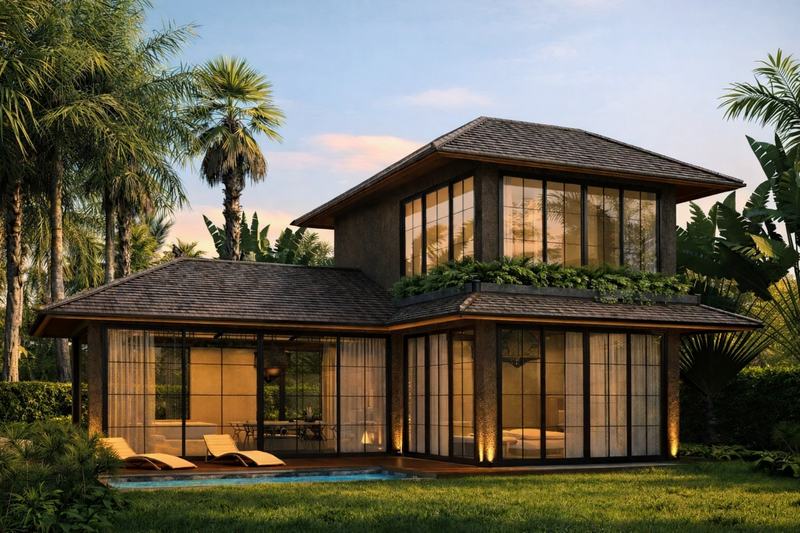
Invest in Bali villas with the yield and the paperwork checked first
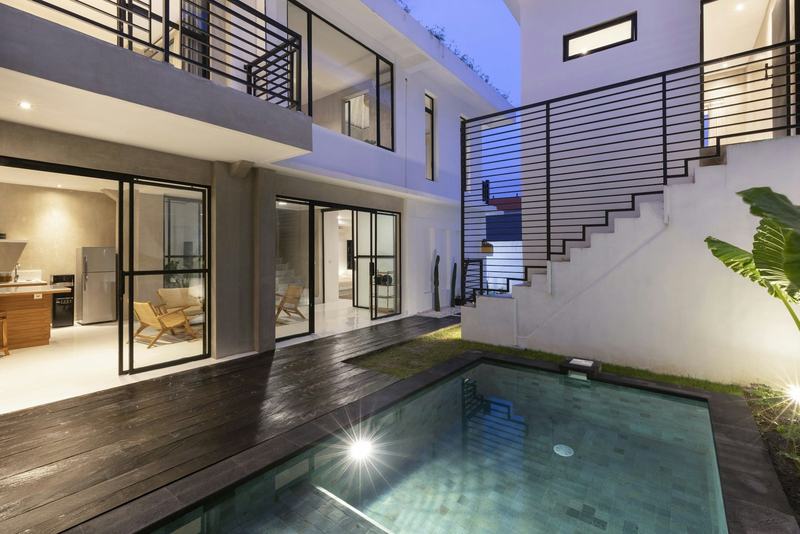
We sell developer villas and completed homes in rupiah, at list price. Every listing shows the income left after management, tax and upkeep. We check the land and permits before you pay a deposit. Properties from Rp 1.59 bn
15+brokers, lawyers and analysts working on your purchase
3,000+developer and resale units in our search base, not just our own listings
0%fee for buyers: the seller pays our commission
Freelegal check of any property before you pay a deposit
Market
Why Bali: demand, yields and the honest caveats
We've been on the island since 2010. We saw this market through the 2022 hype and the 2026 correction. These are the four numbers we actually run deals on, each with a source and a date, none of them from a brochure.
before expenses
10–14%
Gross rental yield
Villas and apartments on short-term rental: nightly rate × occupancy. Hotels aren't included.
to your account
8–12%
Net yield
About 60% of revenue stays with you: 18% goes to the management company, 10% to taxes and 12% to vacancy and upkeep.
our segment
65–80%
Occupancy
For properties in our segment with professional management. The island-wide average is about 37%.
2025
16.3 million
Visitors
6.95 million international visitors and about 9.3 million domestic ones. In 2026 arrivals leveled off at that record high: 3.9 million foreigners in January–July, down 1.98% year over year.
Bali vs. Dubai vs. Phuket
Where your money works harder
Buyers compare us with the UAE and Thailand all the time, and they're right to. We compare by the money that reaches your account, not by advertised percentages. Every market quotes its before-expenses figure in its own favor.
Bali higher yield
8–12%
net per year in strong locations
Entry
Rp 1.59–2.65 bn
Ownership
a 25–35 year lease
Occupancy
65–80%, year-round
VS
Dubai
4.5–6%
net per year after fees and taxes
Entry
Rp 3.54–5.31 bn
Ownership
full freehold
Occupancy
85–90% in winter, 55–65% in summer
Scroll the table sideways
Metric
Bali
Dubai
Phuket
Income before expenses, the figure ads usually quote
10–14%villas and apartments on short-term rental, hotels excluded; platform data for 2026
6–8%our estimate for short-term rentals in tourist areas
7–9%our estimate for strong projects near the beach
What you actually keep
8–12%in strong locations; 6–10% for an average property
4.5–6%after fees, taxes and service charges
3.8–5.2%with six months of low season factored in
Entry price for a quality property
Rp 1.59–2.65 bnan apartment in an established area like Canggu, or a villa next door in an area still being built out
Rp 3.54–5.31 bna studio or one-bedroom in an area that's easy to sell in
Rp 1.77–2.65 bna condo apartment close to the beach
Occupancy and seasonality
65–80%holds up year-round: high and low season differ by 10–15 points
85–90% in winter, 55–65% in summerJune through August is hot, and demand nearly halves
80–90% from November to April, 40–55% in the rainsthe rainy season takes out roughly half the year
What a foreigner can own
a 25–35 year leaseleasehold with an extension right; also right-to-use title (Hak Pakai) or buying through your own foreign-owned company (PT PMA)
full freeholdno time limit, but only in zones designated for foreign buyers
freehold on apartments onlyand foreigners combined can own no more than 49% of a building's floor area; villas are leasehold for up to 30 years
The honest caveat
The rules here are young, and in 2026 they got stricter: a property without a valid rental license (NIB) gets delisted from booking platforms. That hurts anyone who built around the rules. For legal properties it's protection against price dumping. We check the zoning and permits before your deposit, not after.
The most transparent of the three: the transaction registry is public, money moves through escrow, and buyer rights are protected. The price of that is an entry ticket twice as high, and rents that grow slower than prices. Income gets squeezed between an expensive purchase and a steady flow of new builds.
A mature market, and that cuts both ways: besides new projects, you're competing with hundreds of owners selling below list. Add six months of low season and visitor numbers that have stopped growing.
Sources: Global Property Guide and the rental platforms AirROI and AirDNA, 2026. Dubai and Phuket figures are market benchmarks. For any specific property we always run the numbers separately.
Bali market data
Demand is back. Here's where it pays
Three numbers we check before recommending anything: how many visitors come, how full rooms get through the year, and what a villa really earns in each area.
Foreign arrivals
BPS Bali · 2019, 2023–2026
Direct foreign arrivals passed the 2019 peak in 2024 and hit a record 6.95 million in 2025. January to July 2026 brought 3.90 million, 1.98% below the same months of 2025, and July turned positive again.
Direct foreign arrivals to Bali: 6.28 million in 2019, 5.27 million in 2023, 6.33 million in 2024, 6.95 million in 2025, and 3.90 million in January to July 2026
Year
Arrivals
2019
6,275,210
2023
5,273,258
2024
6,333,360
2025
6,948,754
2026, January–July
3,900,965
*2026: January–July. Source: BPS Bali, direct foreign arrivals, release of September 1, 2026. Full data →
Hotel occupancy by month
BPS Bali · star-rated hotels · 2025–2026
Rooms fill to about 70% in July and August and drop to 47% in March. 2026 runs close to 2025, with a stronger first quarter. Plan a villa's year around the slow months, not the peak.
Star-rated hotel occupancy in Bali by month in 2025 and January to July 2026, from 46.6% in March 2025 to 69.5% in August 2025
Month
2025
2026
1
60.3%
56.7%
2
51.6%
55.4%
3
46.6%
52.5%
4
57.2%
57.9%
5
58.1%
61.2%
6
64.7%
64.9%
7
67.8%
67.3%
8
69.5%
—
9
68.2%
—
10
64.6%
—
11
58.0%
—
12
60.9%
—
Source: BPS Bali, monthly tourism releases through July 2026. Full data →
What a villa earns a year
AirROI · revenue per listing · last 12 months
Average yearly revenue per short-term rental listing, in rupiah. The owner keeps about 60% after management, upkeep and tax. Managed villas beat these averages.
Average yearly revenue per short-term rental listing by area: Seminyak Rp 514 million, Uluwatu Rp 491 million, Pererenan Rp 386 million, Canggu Rp 376 million, Ubud Rp 206 million
Area
Revenue per listing
Occupancy
Seminyak
Rp 514 million
38.0%
Uluwatu
Rp 491 million
46.2%
Pererenan
Rp 386 million
40.2%
Canggu
Rp 376 million
36.2%
Ubud
Rp 206 million
36.6%
Source: AirROI short-term rental data, checked September 2026, converted to rupiah at the site rate. Industry data: BPS does not publish villa revenue. Full data →
Featured
Featured villas and apartments
One unit per project, each with its own photos, the developer price and a net yield from our model.
We don't push our own shortlist. We pick from the whole market
Most agencies on the island hold a dozen projects under contract, and those are what you'll be shown. We work differently, and here's what that changes for you in practice.
3 000+units listed
500+developers in our database
RU / ENwe see both sides of the market
0%you pay us nothing, the seller pays the commission
Swipe for more cards
01
We choose from the market, not from a house list
Our database holds more than 3,000 units from over 500 developers, including completed homes and standalone villas. So the conversation starts with what you need, not with "here's what we've got."
02
The half of the market you usually don't get shown
A strong share of supply comes from European and English-speaking developers: small boutique projects with a name on the island that sell well later. Many agency shortlists skip them. We cover both sides of the market.
03
The seller pays us, not you
The developer has already built our fee into the price, so you pay nothing extra for us. On some projects, buying through us even comes out cheaper. We also have no reason to steer you toward a particular project: we earn the same whichever one you pick.
04
We check before the viewing, not after the booking
Zoning, the permit chain, the remaining lease term, the reputation of the developer and the management company. If a project fails our checks, you simply never hear about it. That's more honest than explaining later why you should walk away from the deal.
05
An investment and a home are different properties
They're easy to mix up, and that's exactly where people lose money. We start with your goal and what you'll actually keep, then look at options. Skipping a bad deal beats closing one.
06
We stay after you sign
Handover inspection, rental launch, management, and selling when you're ready. Selling once and disappearing doesn't pay for us: in this market people know us through repeat clients and referrals.
What we do
What we do to keep your Bali purchase safe
In a Bali deal the risk sits in the paperwork and the numbers, not the villa. We deal with both before you commit, and as a buyer you pay us nothing.
Finding the right property
We search 3,000+ developer and resale units, not just our own listings, and send three to five that fit your budget and goal, with gross and net yield worked out for each.
A shortlist with the numbers done
Video viewings on site
Payments tied to construction stages
Checks before your deposit
Title, zoning, building approval and the developer's record, checked at our cost. You get a written report with every open question before any money moves.
Land certificate and who owns it
Zoning (RDTR) that allows your plan
Building approval (PBG) and developer track record
Where the gap between the advertised yield and the money in your account goes
The "14% a year" you see in ads is income before expenses. Out of it come the management company, taxes, vacancy and repairs, and what reaches you is noticeably less. We show the whole path of the money up front, not after you've paid a deposit. Work through this math once and you'll read every other number on this page the way we do.
Running the numbers on:
Occupancy 70%Base
Rp 176 million
net per year
Revenue before costsRp 294 million
Costs 40%Rp 118 million
Net yield9.1% a year
Payback11.0 years
Occupancy 80%Optimistic
Rp 202 million
net per year
Revenue before costsRp 336 million
Costs 40%Rp 134 million
Net yield10.4% a year
Payback9.6 years
Occupancy 60%Pessimistic
Rp 151 million
net per year
Revenue before costsRp 252 million
Costs 40%Rp 101 million
Net yield7.8% a year
Payback12.8 years
Management company 18%
Taxes 10%
Vacancy and upkeep 12%
Left for the owner 60%
ROI before costs 15.1% → net 9.1% (base case)
Occupancy 70%Base
Rp 298 million
net per year
Revenue before costsRp 497 million
Costs 40%Rp 199 million
Net yield8.9% a year
Payback11.3 years
Occupancy 80%Optimistic
Rp 341 million
net per year
Revenue before costsRp 569 million
Costs 40%Rp 227 million
Net yield10.1% a year
Payback9.9 years
Occupancy 60%Pessimistic
Rp 256 million
net per year
Revenue before costsRp 426 million
Costs 40%Rp 171 million
Net yield7.6% a year
Payback13.1 years
Management company 18%
Taxes 10%
Vacancy and upkeep 12%
Left for the owner 60%
ROI before costs 14.8% → net 8.9% (base case)
Occupancy 70%Base
Rp 705 million
net per year
Revenue before costsRp 1.18 bn
Costs 40%Rp 470 million
Net yield8.7% a year
Payback11.5 years
Occupancy 80%Optimistic
Rp 806 million
net per year
Revenue before costsRp 1.34 bn
Costs 40%Rp 538 million
Net yield9.9% a year
Payback10.1 years
Occupancy 60%Pessimistic
Rp 605 million
net per year
Revenue before costsRp 1.01 bn
Costs 40%Rp 403 million
Net yield7.4% a year
Payback13.4 years
Management company 18%
Taxes 10%
Vacancy and upkeep 12%
Left for the owner 60%
ROI before costs 14.5% → net 8.7% (base case)
Detailed breakdown: three scenarios after all costs
Per year
Base
Optimistic
Pessimistic
Nightly rate
Rp 1.2 million
Rp 1.2 million
Rp 1.2 million
Occupancy
70%
80%
60%
Annual revenue
Rp 294 million
Rp 336 million
Rp 252 million
Total costs
Rp 118 million
Rp 134 million
Rp 101 million
– Management, 18%
Rp 52.9 million
Rp 60.5 million
Rp 45.4 million
– Taxes, 10%
Rp 29.4 million
Rp 33.6 million
Rp 25.2 million
– Vacancy and upkeep, 12%
Rp 35.3 million
Rp 40.3 million
Rp 30.2 million
Net to the owner
Rp 176 million
Rp 202 million
Rp 151 million
Net yield, % a year
9.1%
10.4%
7.8%
Payback, years
11.0
9.6
12.8
Where the revenue goes · base case
60%to the owner
Left for the owner60%
Vacancy and upkeep12%
Taxes10%
Management company18%
Base case
Rp 14.7 million
per month to the owner, on average
9.1% net a year
Rise Real Bali estimate, not a guaranteed income. Calculation for "Apartment · Rp 1.97 bn" at a nightly rate of Rp 1.2 million; occupancy 70% / 80% / 60% are model assumptions; costs are 40% of revenue, including 10% tax. The rate is an estimate based on comparable properties in the area.
Per year
Base
Optimistic
Pessimistic
Nightly rate
Rp 1.9 million
Rp 1.9 million
Rp 1.9 million
Occupancy
70%
80%
60%
Annual revenue
Rp 497 million
Rp 569 million
Rp 426 million
Total costs
Rp 199 million
Rp 227 million
Rp 171 million
– Management, 18%
Rp 89.5 million
Rp 102 million
Rp 76.8 million
– Taxes, 10%
Rp 49.7 million
Rp 56.9 million
Rp 42.6 million
– Vacancy and upkeep, 12%
Rp 59.7 million
Rp 68.2 million
Rp 51.2 million
Net to the owner
Rp 298 million
Rp 341 million
Rp 256 million
Net yield, % a year
8.9%
10.1%
7.6%
Payback, years
11.3
9.9
13.1
Where the revenue goes · base case
60%to the owner
Left for the owner60%
Vacancy and upkeep12%
Taxes10%
Management company18%
Base case
Rp 24.9 million
per month to the owner, on average
8.9% net a year
Rise Real Bali estimate, not a guaranteed income. Calculation for "1–2 bedroom villa · Rp 3.36 bn" at a nightly rate of Rp 1.9 million; occupancy 70% / 80% / 60% are model assumptions; costs are 40% of revenue, including 10% tax. The rate is an estimate based on comparable properties in the area.
Per year
Base
Optimistic
Pessimistic
Nightly rate
Rp 4.6 million
Rp 4.6 million
Rp 4.6 million
Occupancy
70%
80%
60%
Annual revenue
Rp 1.18 bn
Rp 1.34 bn
Rp 1.01 bn
Total costs
Rp 470 million
Rp 538 million
Rp 403 million
– Management, 18%
Rp 212 million
Rp 242 million
Rp 181 million
– Taxes, 10%
Rp 118 million
Rp 134 million
Rp 101 million
– Vacancy and upkeep, 12%
Rp 141 million
Rp 161 million
Rp 121 million
Net to the owner
Rp 705 million
Rp 806 million
Rp 605 million
Net yield, % a year
8.7%
9.9%
7.4%
Payback, years
11.5
10.1
13.4
Where the revenue goes · base case
60%to the owner
Left for the owner60%
Vacancy and upkeep12%
Taxes10%
Management company18%
Base case
Rp 58.8 million
per month to the owner, on average
8.7% net a year
Rise Real Bali estimate, not a guaranteed income. Calculation for "3-bedroom villa · Rp 8.12 bn" at a nightly rate of Rp 4.6 million; occupancy 70% / 80% / 60% are model assumptions; costs are 40% of revenue, including 10% tax. The rate is an estimate based on comparable properties in the area.
Location
Bali areas: where to buy a villa or apartment
We work with these areas every day, so here it is straight: there's no "best area." There are stages of maturity. A cheaper entry means more upside and a longer exit. Pick for your goal, not the hype.
Satellite base map from Copernicus Sentinel-2 data (2024–2025), cloud-free composite processed by Rise Real Bali. Area markers show approximate centers.
Core
Canggu Badung · southwest
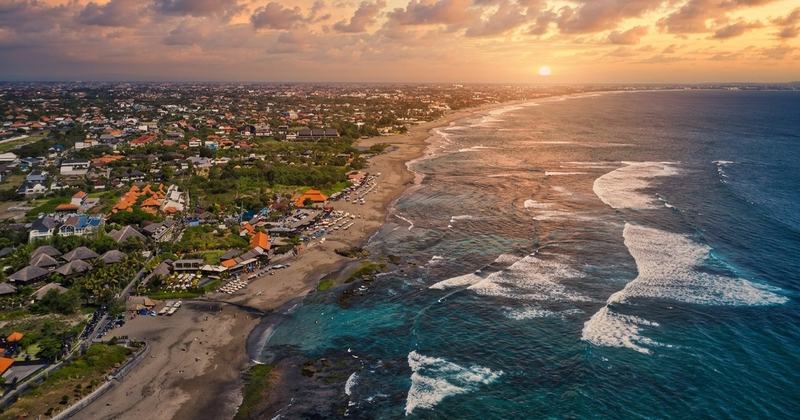
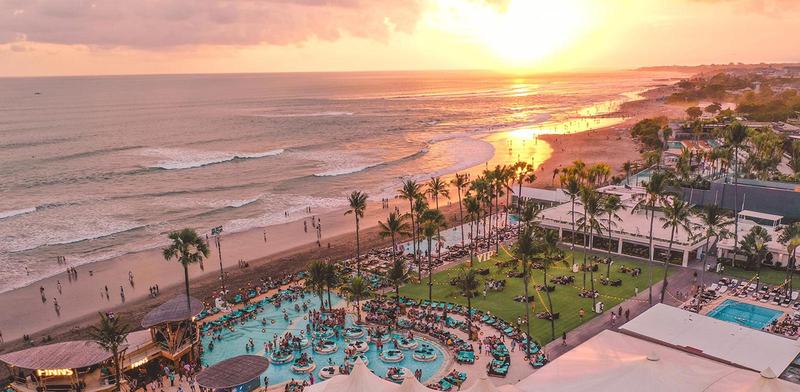
The core of the market: infrastructure and demand are in place, and properties sell faster. Rp 3.9 million a night at 37.5% occupancy, with nearly 4,000 rental listings. Competition is stiff and almost no open land is left.
Dense development with restaurants and beach clubs close by. Liquidity is high, and so are noise and traffic. Legally it's one of the cleanest areas in the south: only 3.6% of listings sit in agricultural or protected zones, against 9.3% island-wide.
The longest rental track record on the island: Rp 5 million a night, the top rate in the south, but 39% occupancy and roughly flat growth. New plots are nearly gone, and the freehold premium over leasehold is the island's largest: a median of Rp 6.6 bn for leasehold against Rp 10.9 bn for freehold.
A quiet residential area a short hop from the core. It suits living and long-term rentals more than nightly stays: a median of Rp 6.4 bn for leasehold and Rp 9.6 bn for freehold. People who live in Bali themselves buy here.
Demand spilled over from Canggu: Rp 3 million a night, 45–48% occupancy, and rental supply up 15% in a year, faster than revenue. Model the property, not the area. 17.3% of listings sit in agricultural or protected zones, so we check zoning before we talk price.
Active construction, with infrastructure catching up to Canggu. The main risk is the green (agricultural) zone, so we check zoning and permits before any talk about price.
The Nuanu City master plan covers 44 hectares, with more than 400 units announced by 2027. The area averages about 50% occupancy and individual villas consistently beat that: the property and its management drive occupancy, not the area.
Surf spot, then cafés, then housing, then prices. Land is cheaper than in Badung and the risk runs medium to high. The Mengwi–Gilimanuk toll road and the metro are plans with no date and no land allocated, so we leave them out of the math.
The Tabanan–Kedungu pair: low entry, long horizon, lower liquidity than the core. The regency sits outside the voluntary development agreement for the south, and zoning (RDTR) doesn't cover everything, so we check each plot's status as of the deal date.
Ocean views and cliffs: Rp 4.3 million a night at 46% occupancy, the best combination in the south. But 26.1% of listings sit in agricultural or protected zones. We pick properties with an edge nobody can build over: the view, the front row, beach access.
The center of the island with its own crowd: Rp 2.1 million a night at 37.7% occupancy and revenue up 16.5%, the island's best over the past year. Supply is growing fast, so we go in with a model, not a feeling.
A calm east coast with family demand and the KEK medical cluster, where 62% of hospital patients are foreigners. Rp 1.5–1.8 million a night at about 40% occupancy, and revenue is barely growing. The ferry to Nusa Penida takes 40–45 minutes from here.
The ITDC resort enclave: hotel-grade development, security, engineering and management. What sets it apart is a near-zero freehold premium over leasehold, so there's nothing to overpay for in the ownership type. In the catalog: Nai by Vibe and Ramada by Wyndham.
Wild coastline south of Uluwatu, at an early stage. We check access, roads, water and power for every property: none of it comes by default here, and Perda 3/2026 locked in public access to the shoreline.
The east of the island, an early market. The anchor is SALT of Virgin Beach, an 84-key resort slated to open in Q1 2028. The developer's own materials give yields a year apart, so we model it on our own scenario.
The village hub of southern Uluwatu, where the peninsula's services cluster. Rp 4 million a night at 42% occupancy. The highest zoning risk in the south: 27.9% of listings sit in agricultural or protected zones. We check water and access roads for every property.
A boutique cliffside area: 59% occupancy, the highest in the south, at Rp 3.2 million a night, and properties sell twice as fast as the island average. Hotels and villas aren't allowed in the beach zone, only simple cafés, and shoreline improvements have been underway since July 2026. We look at the legal side before the price.
Southern Uluwatu by the Melasti beach clubs, a fast-growing spot. Steep terrain makes building and access more expensive. In return you get panoramas nobody can build over.
A family beach with daytime tourist traffic: lots of day trips, fewer overnight stays. Entry is lower and the rental model is weaker than in the cliffside areas, so we model it more conservatively.
A calm bay with a fish market and restaurants on the sand, 15 minutes from the airport. Villas up the hill look out over the bay. We have no local sample, so we use the Uluwatu benchmark: Rp 4.3 million a night at 46% occupancy.
A surf beach below the cliff with a flat plateau above it: the lowest entry on the peninsula, a loft villa. We have no local sample, so the figures follow the Uluwatu benchmark.
A wild beach past Nyang Nyang, a 20-minute walk down to the water. Early stage: we check the road, water and power for every plot. Figures follow the Uluwatu benchmark.
The island's first resort area, 15 minutes from the airport, with hotels and malls. There's no open land, so buyers take what's already built. We have no local sample and use the Seminyak benchmark: Rp 5 million a night at 39.4% occupancy.
1.08 million visitors a year, mostly day-trippers: Rp 2 million a night at 26% occupancy and about Rp 142 million in revenue per listing per year. Promises of 70–85% describe high season, not the full year. Risks: water, plot boundaries, permits and a ferry crossing that depends on the swell.
Mountains, lakes, cool air: Rp 1.2 million a night at 27% occupancy, but up 45% in a year, the fastest growth on the island. Developer claims of 20%+ are projections: a nearby project promised 22.6% at 80% occupancy against an actual 27% for the year. We rerun a realistic scenario with you on the call.
The north today: Rp 1.7 million a night at 23% occupancy, and rental listing revenue fell 31% over the year. A northern airport scenario exists, but the project has neither an approved site nor a date, so we don't count it.
Tell Gusti your budget. Get 3–5 villas with the real numbers.
“I'll send villas that fit your budget, with net yield, the lease terms and what we still need to check. No pressure to buy.”
Gusti Ayu, broker at Rise Real Bali
Net yield after management, upkeep and tax
Title, zoning and permit status for each
Free for buyers, the seller pays our fee
Scroll right for more
step 1 of 6
01
First message
You send your budget and goal. We ask five to seven questions and rule out what won't fit before any viewing.
step 2 of 6
02
Shortlist with numbers
Three to five properties, each with gross and net yield, document status and the weak spots.
step 3 of 6
03
Video viewing
A broker walks the site on camera and shows what renders leave out: the neighbors, the access road, how far construction has got.
step 4 of 6
04
Due diligence
Land title, zoning, building approval (PBG) and the developer's record. You get a written report that lists every open question.
step 5 of 6
05
Deposit and contract
The reservation deposit goes in only after the checks. Payments follow construction stages, not the calendar.
step 6 of 6
06
Handover and after
We inspect the unit with you, bring in a property manager and help with the rental license. We stay on after the deal.
Ownership
Can foreigners own property in Bali?
Not as freehold. Indonesian law keeps freehold title (Hak Milik) for citizens. Foreign buyers take a long leasehold in their own name, hold a right-to-use title (Hak Pakai) with a residence permit, or own through a foreign-owned company (PT PMA). All three are legal, and most foreign buyers in Bali use the first.
01
Leasehold (Hak Sewa)
Who can use it
Anyone, in your own name. No residence permit needed.
Term
Usually 25–30 years. Extensions are set in the contract.
What to watch
The extension clause and its price formula. Without them the asset shrinks every year.
02
Right-to-use title (Hak Pakai)
Who can use it
Foreigners who hold an Indonesian residence permit (KITAS or KITAP).
Term
30 years, extendable by 20 and renewable by 30.
What to watch
It covers a home you live in. Minimum prices apply and vary by province.
03
Foreign-owned company (PT PMA) with a right to build (HGB)
Who can use it
A company you set up, with a business code that allows rentals.
Term
HGB for 30 years, extendable by 20 and renewable by 30.
What to watch
Capital requirements, yearly reporting and accounting. It pays off for a rental business or several units.
Sources: Basic Agrarian Law No. 5/1960; Government Regulation No. 18/2021 on land rights. Lease terms vary by contract.
Don't take our word for it. Check us: who we are, what we built ourselves and how we make money.
Company
RISE REAL BALI
We're an international team in Bali investment property. We've known the island since 2010: first we built and managed, and since 2023 we've run an agency with its own research team. We see this market from both sides, as builders and as sellers, so we judge a price by what it costs to build, not by the listing. We work with more than 500 developers and know who delivers on time and whose paperwork needs a second look.
We sell what doesn't show up in open listings: rare lots, land to build on, operating hotels. If you need it, we also consult and run turnkey construction. Bali is home for us, and we sell it the way we'd buy ourselves: first a house you want to live in, then the income it brings.
We built it ourselves
Our own project: Rise Villas near Nuanu
Villas from Rp 3.36 bn in Nyanyi, next to Nuanu. We don't only sell other people's projects: we built this one and own it ourselves, from the land and the budget to the first guests. So we speak the same language as developers, and we spot where a project's economics don't add up before a buyer does.
Brokers, a lawyer, marketing and rental management are all on staff, not outsourced. Document checks, yield modeling and your rental launch stay in one set of hands instead of getting split across three contractors.
What changed in the last two weeks for buyers and owners: tourist numbers, rules, flights and Badung budgets. Each item says why it matters for a villa or apartment.
Economy
Fuel returns to Bali pumps: a 20,500 kl tanker has docked, 26,200 kl more is on the way
Many Bali petrol stations saw long queues for Pertalite and Pertamax because of tight quotas. On Sunday, October 11, a tanker carrying 20,500 kilolitres docked at Manggis: 18,000 of Pertalite and 2,500 of Pertamax. Pertamina has added a further 26,200 kilolitres, with ships due on October 12, 14 and 16 at the Denpasar and Karangasem terminals. The island burns about 2,200 kilolitres of Pertalite a day. Officials expect supply to normalise within one to two days.
Why it matters: The disruption is one-off and supply is being restored within days. Ask your management company how it handles guest transfers on such days.
Source: ANTARA News Bali
New spaces
Kura-Kura Bali zone is being pitched as an AI hub, with Rp 1.8 trillion invested to date
The government wants the Kura-Kura Bali Special Economic Zone to become a hub for AI and semiconductors. It is building on cooperation with the Tsinghua Southeast Asia Center, which already runs physics and neuroscience programmes there. Cumulative investment in the first half of 2026 reached Rp 1.8 trillion. The zone employs 2,173 people and logged 131,657 visits. Indonesia has 25 special economic zones in total.
Why it matters: The zone is growing into a separate business district of the island. Over time, places like this create demand for mid-term rentals.
Source: ANTARA News Bali
Visas & law
Two foreigners deported from Denpasar for practising medicine without an ITAS or licence
Denpasar Immigration has deported two foreign nationals. They arrived in July on visitor visas. They then treated patients in secret at a private Denpasar hospital, with no residence permit and no medical licence. The case began with tip-offs from residents. The legal basis is Law No. 6 of 2011 on Immigration, which allows administrative sanctions and expulsion for breaking local rules.
Why it matters: Working on a visitor visa is not allowed; you need a work ITAS. This matters to anyone planning to run a rental or a business in Bali personally.
Source: ANTARA News Bali
Infrastructure
Kuta speeds up its pedestrian zone and beach protection; 85 km of coast needs Rp 4 trillion
Badung Regency is speeding up a coastal project along Kuta, Legian and Seminyak. It covers a pedestrian zone and full beach restoration. According to the Ministry of Public Works, Bali’s coastline is 633 km long and about 215 km is hit by erosion. From 2007 to 2025, Rp 1.2 trillion was spent on 130 km. Another 85 km remains critical, estimated at Rp 4 trillion.
Why it matters: Kuta’s beach and seafront underpin rental demand nearby. If you are buying close to the water, ask the developer about the state of the shoreline.
Source: detikBali
Infrastructure
South Kuta went a week without clean water; desalination and wastewater recycling are on the table
Residents of South Kuta spent about a week without clean water. The provincial government asked Badung to make it a first priority. The regent says groundwater cannot keep up with a growing population. Options include seawater desalination, already running in Klungkung, and wastewater recycling with membrane bioreactors. Desalination is seen as the best fit for Pecatu. For now, the district is adding pipes to lift water up to the hills.
Why it matters: Water is the main engineering question on the Bukit. Before buying, check the source: borehole, mains or trucked in.
Source: detikBali
Visas & law
Bali designates six low-emission zones: Kuta, Ubud, Sanur, Nusa Dua, Nusa Penida and central Denpasar
The province and four local governments signed a low-emission zone agreement for 2026–2030. The list covers Nusa Dua, Nusa Penida, Kuta, Ubud, Sanur and the historic Jalan Gajah Mada in Denpasar. The legal basis is Governor’s Decree No. 912/04/B/HK/2026 of October 6. The zones were picked for tourist numbers. They will use source-separated waste, limit single-use plastic and add solar power. Public and tourist transport is asked to switch to electric vehicles.
Why it matters: Hotels and villas in these areas may face new rules on waste, plastic and energy. Build them into the budget and the management contract.
Source: detikBali
Straight answers
Buying property in Bali: the questions we hear most
Don't see yours? Message us on WhatsApp and we'll answer in writing.
Can a foreigner own property in Bali?
Not as freehold. Indonesia's Basic Agrarian Law (No. 5/1960) reserves freehold title (Hak Milik) for citizens. The workable options are a leasehold in your own name, a right-to-use title (Hak Pakai) if you hold a residence permit, and ownership through a foreign-owned company (PT PMA) holding a right to build (HGB) on a 30+20+30 year cycle.
How does leasehold differ from Hak Pakai and PT PMA?
Leasehold is a fixed-term lease. What matters is not the headline term but how much of it is left and the extension terms written into the contract. It's the simplest and fastest way in.
Hak Pakai is a right-to-use title registered to an individual with a residence permit. A PT PMA is an Indonesian company with foreign shareholders: it holds the HGB title and can run commercial rentals legally.
What about nominee arrangements?
Putting property in the name of an Indonesian nominee has been a criminal risk since Perda 4/2026, not a "gray area." We don't arrange these deals and don't recommend them.
What's the real yield?
Gross rental yield on Bali villas is about 5.8% in Global Property Guide's Q1 2026 data. The only fair way to compare markets is by net yield: Bali 6–10%, 8–12% in strong locations with professional management; Dubai 4.5–6%; Phuket 3.8–5.2%.
Between gross income and the money in your account sit management, taxes, vacancy and repairs, which take 30–50% of revenue. Any model is a projection, not a guarantee: actual income depends on occupancy, season, management quality and the IDR exchange rate.
Do you need an NIB, and what changed on August 1, 2026?
A legal short-term rental needs the full chain: a pink (tourism) zone under the RDTR → a building approval (PBG) → a certificate of occupancy (SLF) → a rental license (NIB). Since August 1, 2026, booking platforms have been delisting properties without a valid rental license, so a missing document now hits occupancy directly.
Can I buy remotely?
Yes. Viewings run on Zoom, the paperwork is done remotely, and we handle the handover inspection. You don't have to fly to the island.
Who manages the rental?
The property's own management company or one of our partners. Market fees run 15–25% of revenue, and resort operators charge up to 35%. Our models on the site assume 18% for a standard manager and 25% for a resort. In the contract we check the fee, who pays for supplies, how vacancy is counted and what the owner reports look like.
How do I sell later?
Leasehold is sold by assigning the lease. A property held in a PT PMA is sold as an asset or as a share of the company. How fast you exit depends on the area: in the core (Canggu, Uluwatu, Ubud) buyers turn up faster than on the frontier. We show the expected exit timeline and price for the specific property before the deposit, together with the income model.
How much do your services cost?
The price is the same as buying direct from the developer. The seller pays our commission.
What payment schedules do developers offer?
The payment schedule comes from the developer: typically 20–30% up front, with the balance in equal installments until handover. Terms vary by project, and the exact schedule is in each project's price list.
What about taxes?
Your tax burden depends on the ownership structure (leasehold, Hak Pakai, PT PMA), your tax residency and how you rent the property out. Our models on the site assume 10% of rental revenue, the base rate for short-term rentals. We work out the exact rates, filing and tax on sale for your situation with an Indonesian lawyer and tax advisor before the deposit.
Which areas do you cover?
Most of our deals happen on the southwest coast from Seminyak and Canggu out to Pererenan, Seseh, Nyanyi, Kedungu and Tabanan, on the Uluwatu peninsula, in Ubud, Nusa Dua and Sanur. The catalog covers 23 areas in all. In the east and north we list individual projects and say plainly when we have no local rental data.
Contact
Tell us your budget. We'll send three to five properties with the numbers
It's free for buyers: the developer pays our commission, so your price is the same as buying direct. A broker replies within an hour during Bali business hours (UTC+8).